 ع

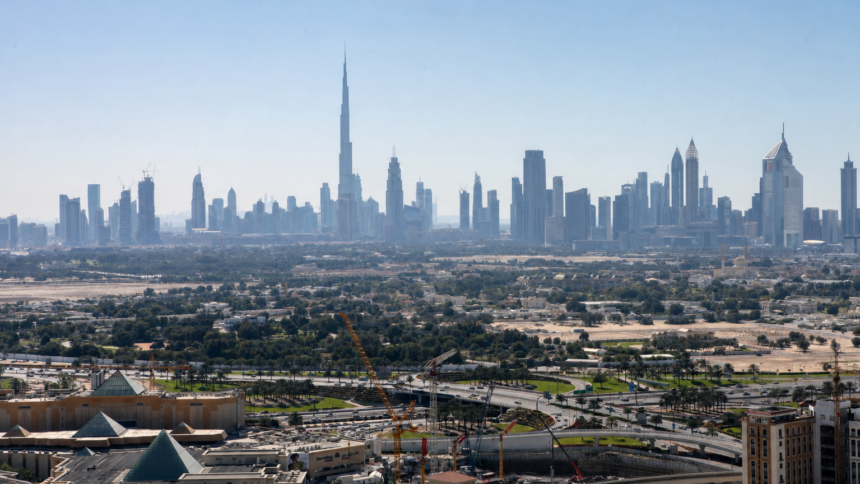
The report by property consultants Cavendish Maxwell attributed the slowdown to heightened buyer caution following the outbreak of conflict in late February, noting that the third-quarter statistics incorporate both recent purchases and those agreed earlier as registration lags ease. Ronan Arthur, director and head of residential valuation at the firm, explained that the data confirms a shift toward more measured purchasing activity in the period after the conflict began. Arthur added that this pattern aligns with expectations of reduced momentum in what had been a high-performing market.
Off-plan properties continued to lead activity, representing 72 percent of all transactions and 65 percent of total sales value during the quarter, according to the consultancy’s breakdown. This segment’s resilience occurred even as overall deal flow contracted markedly from the prior year. Secondary market transactions experienced similar proportional declines in both count and aggregate value.
Cavendish Maxwell figures show that over the first nine months of 2026, residential sales volumes fell 23 percent to 112,580 transactions while their total value decreased 27 percent to AED 292 billion. The cumulative data underscores how the third-quarter weakness contributed to a broader cooling after several years of robust expansion. Market participants have pointed to external geopolitical factors as a primary driver behind the changed sentiment.
A separate assessment by S&P Global Ratings, based on Dubai Land Department statistics, placed average monthly transaction volumes at 12,644 between March and September, marking a 26 percent decline from the January-February mean. Industry compilations referenced in the ratings report also indicated price adjustments ranging from 5 percent to 15 percent between late 2025 and September 2026. These movements reflect an ongoing rebalancing as higher inventory levels meet selective demand.
Property consultants have observed that the current environment contrasts with the exceptional transaction levels recorded in 2025, when quarterly volumes frequently exceeded 50,000 sales. The Dubai Land Department data incorporated in multiple analyses highlights how off-plan registrations have moderated while ready properties maintain a steadier, albeit lower, trajectory. Arthur noted in the Cavendish Maxwell release that further clarity on underlying demand will emerge as registration backlogs fully clear in coming months.
Dubai’s residential market has absorbed these adjustments without widespread disruption to ongoing developments, with off-plan sales still comprising the majority of activity across key districts. The consultancy’s review of the first three quarters points to sustained interest in specific segments despite the overall contraction. Additional reporting from sector trackers confirms that average transaction sizes have also adjusted downward in response to the prevailing conditions.