 ع

Kuwait’s KD30 billion borrowing framework has widened its financing options. As Kearney names its first Kuwaiti managing director in the country, the wider story concerns how institutions translate new financial capacity into investment decisions, accountable partnerships and public services.
Kuwait has given itself a longer financial horizon. Its Financing and Liquidity Law establishes a public debt ceiling of KD30 billion and permits financial instruments with maturities of up to 50 years, creating a framework through which decisions taken today can carry obligations well into the future.
That makes the institutions responsible for selecting investments, managing commitments and assessing results central to the country’s next phase of development. The ability to raise financing is one part of the process. Determining how that financing should be deployed, and who remains responsible for the outcome, is another.
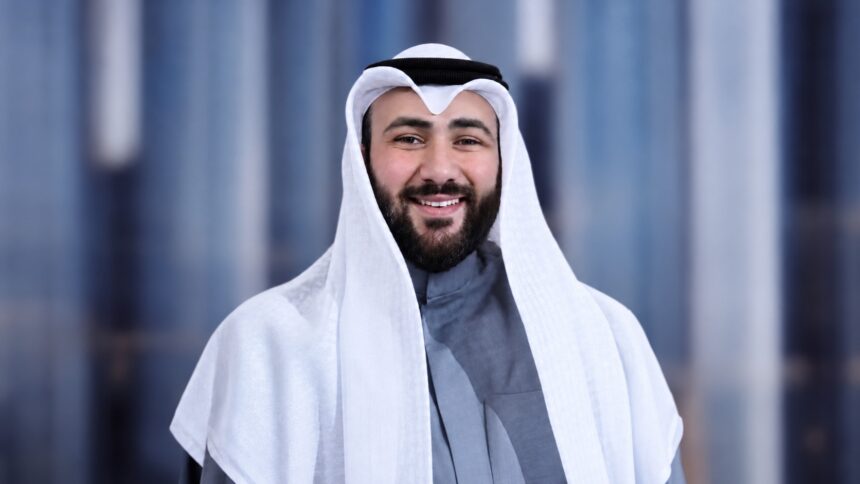
Against this backdrop, Kearney has appointed Dr Bader Khraibut as Partner and Managing Director of its Kuwait business. According to the firm’s announcement dated 21 October, he is the first Kuwaiti to hold the position. His remit covers strategy, business growth, client relationships, project delivery and local talent development, bringing together the commercial and institutional responsibilities that increasingly intersect in Kuwait’s investment agenda.
A financing law with consequences beyond borrowing
The Ministry of Finance’s announcement of Decree-Law No. 60 of 2025 set out both the KD30 billion ceiling and the provision for maturities reaching 50 years. These figures describe the legal framework for borrowing; they should not be read as an amount already raised or a single programme of spending.
The distinction matters because financing authority and investment approval answer different questions. A government may have access to capital while still needing to determine which projects merit funding, how expenditure should be phased and what continuing costs an asset will create once construction is complete.
In its May 2025 explanation of the financing strategy, the ministry identified infrastructure, health, education and energy among the intended development areas. It also described a five-year financing strategy for 2025–2030 and an ambition to develop a domestic yield curve, providing a reference for the local debt market.
For institutions assessing long-lived assets, these are connected developments. The cost and maturity of financing influence which investments are affordable, while the timing of procurement, construction and operations determines when the public receives the intended service. A financing plan therefore needs to remain connected to the practical timetable of the investment it supports.
Where public policy meets private capital
The scale of Kuwait’s proposed investment programme gives those decisions significance beyond individual transactions. In its 2025 Article IV staff report, published in February 2026, the International Monetary Fund described announced public investments in housing, electricity and water, and transport infrastructure amounting cumulatively to 26% of GDP over 2025–2030.
That is a measure of announced plans, rather than completed investment. It nevertheless illustrates the breadth of decisions facing public bodies, financiers and prospective delivery partners.
Housing provides a particularly tangible example. The same report recorded more than 105,000 families awaiting government housing allocations and announced public-private partnership projects intended to provide 185,000 housing units. Those figures describe different parts of the housing programme, rather than homes already delivered against a waiting list.
For a family, the relevant outcome is access to a home. For the institutions arranging delivery, that outcome depends on a chain of decisions concerning land, infrastructure, financing and the allocation of responsibilities. Contracts connect those decisions by specifying what each party must provide and what happens when circumstances change.
The legal and commercial work therefore meet at a practical point: defining obligations clearly enough for a project to proceed and for performance to be assessed throughout its life.
A leadership remit across institutions and investment
Khraibut’s background, as described in Kearney’s announcement, spans strategy consulting, investments and public policy. He has advised government institutions, investors and businesses across Kuwait and the GCC on capital allocation, organisational performance and strategic transformation.
That combination is relevant to an investment environment in which public objectives and commercial decisions frequently sit within the same project. A public institution may be concerned with service coverage and affordability; an investor must also examine returns, operating costs and the risks attached to a long-term commitment. Understanding both perspectives helps define the decisions that require agreement.
“We are building a long-term presence in Kuwait, to be the partner leaders turn to when the decisions matter most,” said Claudio Campanini, Kearney’s Regional Chair for the Middle East and Africa.
Campanini pointed to Khraibut’s experience across public institutions and private capital, alongside his understanding of the Kuwaiti market. The announcement does not identify a Kearney role in the financing law or the housing projects. Those developments provide the national context for the appointment, rather than evidence of a specific advisory mandate.
Khraibut also holds a Master of Public Health in Health Care Management from Yale University and a medical degree from RAK College of Medicine. His qualifications add a public-service dimension to a career now centred on organisational and investment decisions.
Making responsibility measurable
The institutional question extends beyond the moment a contract is signed. A new asset creates operating requirements, maintenance costs and service obligations that continue for years. Assessing its value requires attention to those continuing responsibilities as well as the initial transaction.
In its February 2026 assessment of Kuwait, the IMF recommended periodic public investment management assessments and the tracking of contingent liabilities. These recommendations concern how infrastructure is governed and how potential future obligations are recognised.
For Khraibut, the stated standard for Kearney’s work is similarly expressed in terms of advice and outcomes.
“We will earn their trust through the candor of our advice, the quality of our work, and the lasting results we help them achieve,” he said.
Kuwait’s financing framework now allows commitments extending over decades. The corresponding institutional task is to preserve a clear line between the decision to invest, the responsibility to deliver and the evidence that a public need has been met. For the people waiting for housing, infrastructure or improved services, that is where financial reform becomes tangible.